Can a phone call tell you more than a credit bureau?
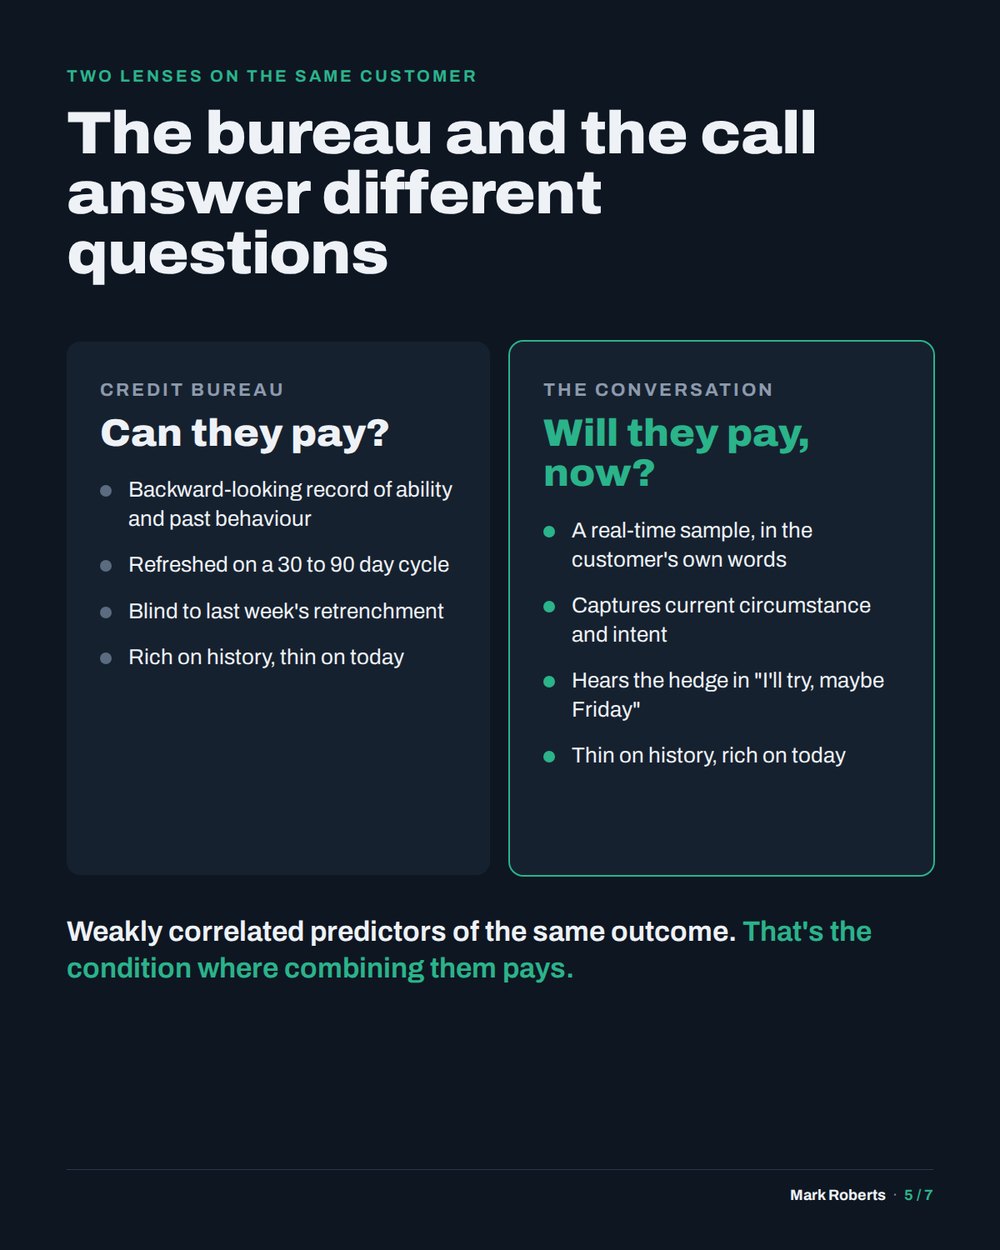
The credit bureau answers one question well: can this customer pay, based on their history? The collections call answers a different one: will they pay, now?
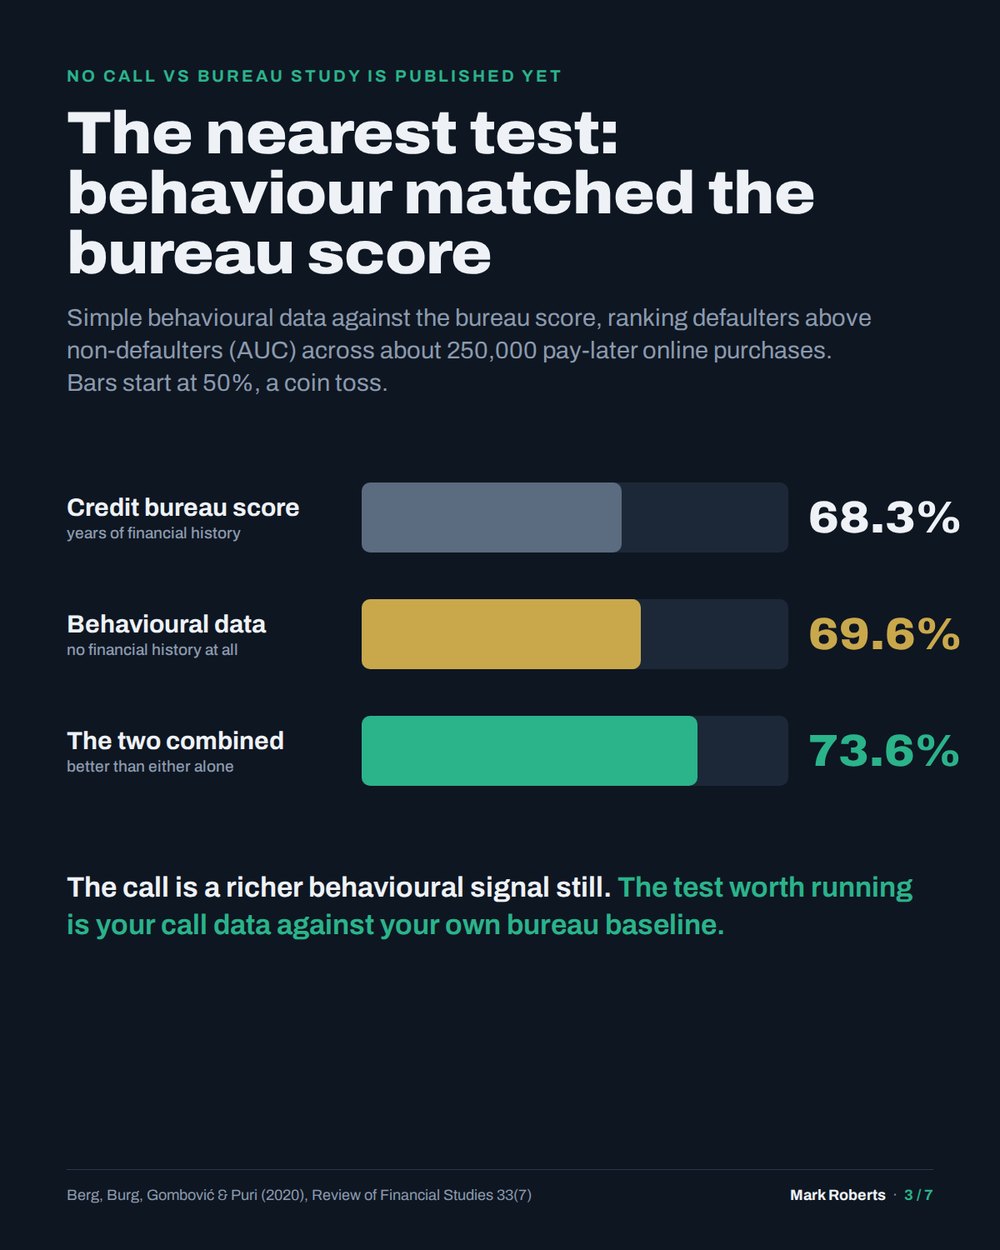
No head-to-head study exists yet, but the nearest test is telling
Across about 250,000 pay-later online purchases, simple behavioural data with no financial history ranked defaulters about as well as the credit bureau score (69.6% against 68.3% AUC). Combined, the two did better than either alone (73.6%).
A call is a far richer behavioural signal than a click trail. The test worth running is your own call data against your own bureau baseline.
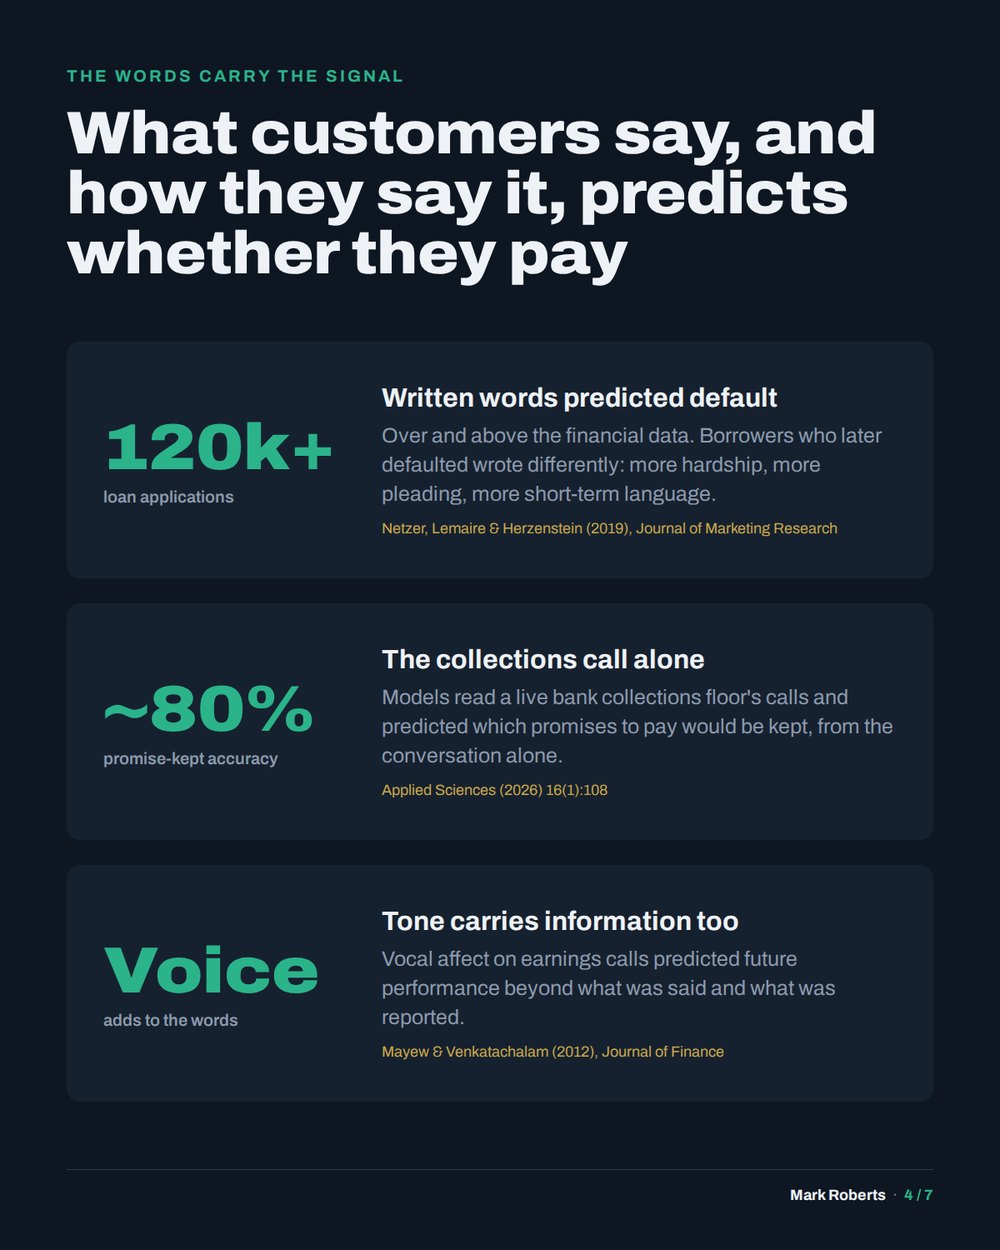
The words carry the signal
- In more than 120,000 loan applications, the words borrowers wrote predicted default over and above the financial data. Borrowers who later defaulted wrote differently, with more hardship and more short-term language.
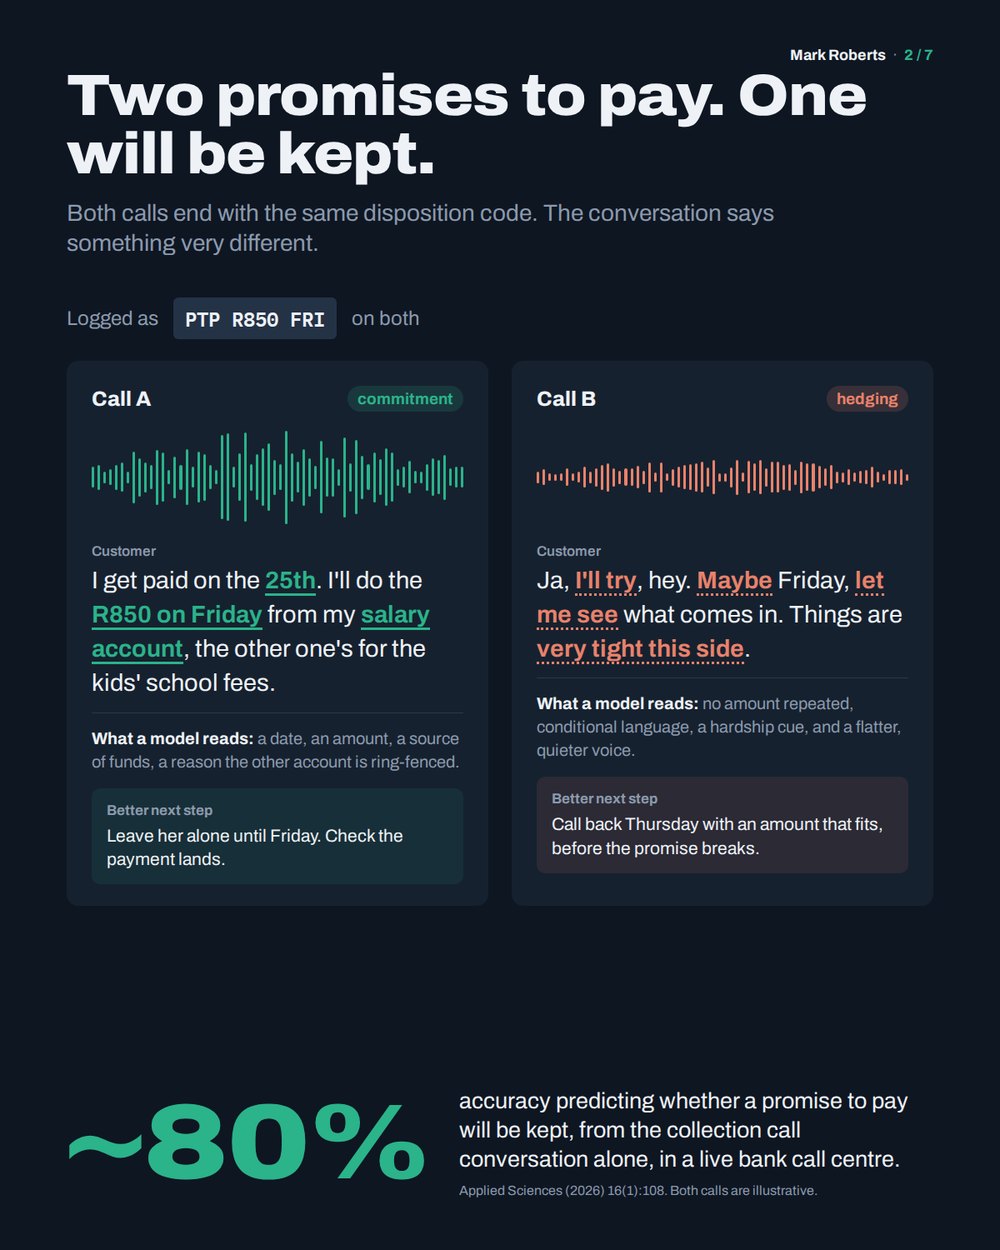
- Models reading a live bank collections floor's calls predicted which promises to pay would be kept with about 80% accuracy, from the conversation alone.
- Tone carries information too. Vocal affect on company earnings calls predicted future performance beyond what was said.
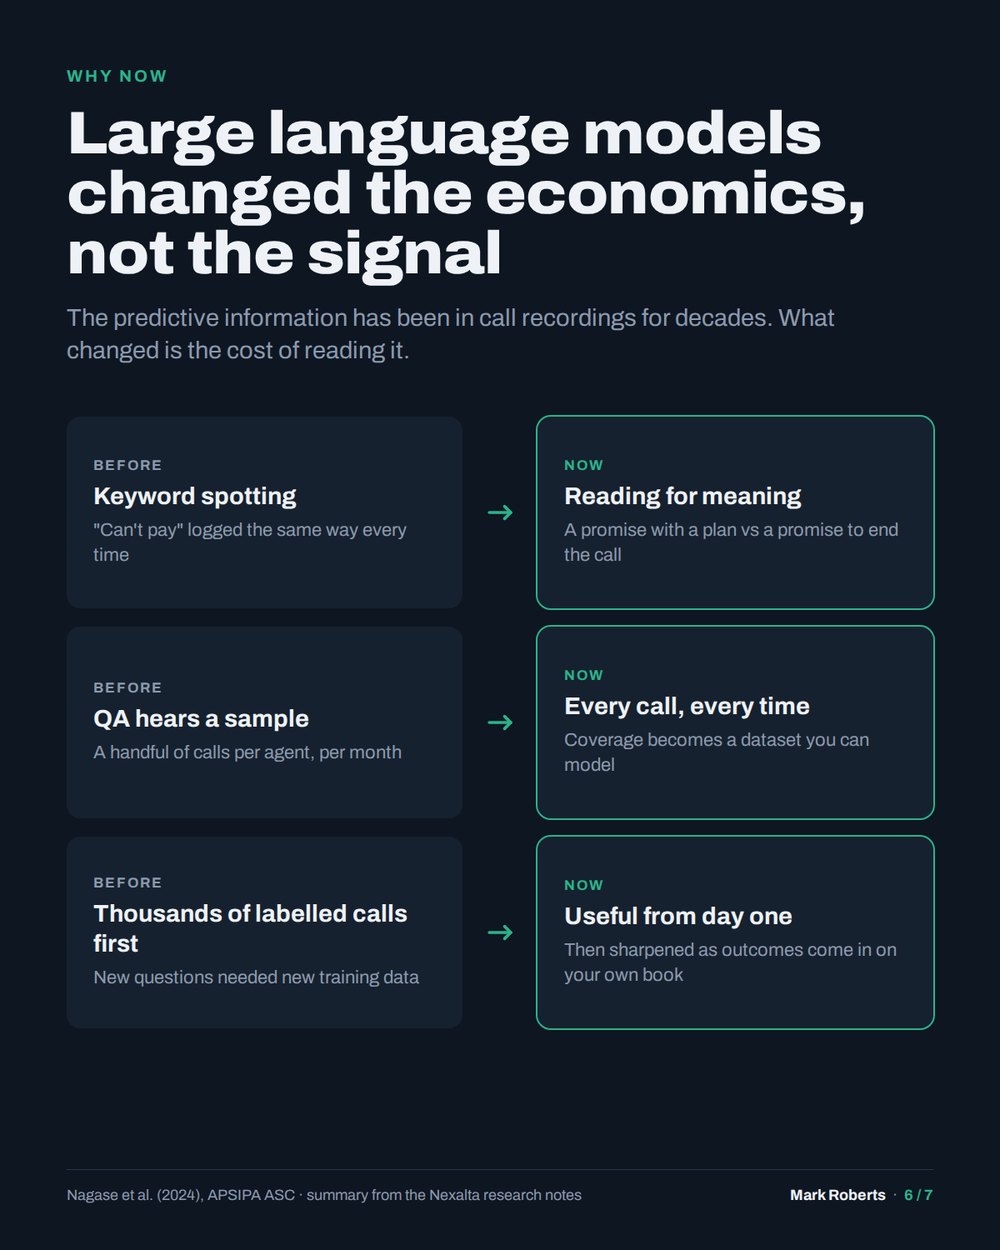
Why now
The predictive information has been sitting in call recordings for decades. What changed is the cost of reading it. Large language models made it practical to hear every call, not a sample.
Sources
- Berg, Burg, Gombović & Puri (2020), "On the rise of FinTechs: credit scoring using digital footprints", Review of Financial Studies 33(7)
- Netzer, Lemaire & Herzenstein (2019), "When words sweat", Journal of Marketing Research
- Applied Sciences (2026) 16(1):108, promise-to-pay prediction from collections calls
- Mayew & Venkatachalam (2012), "The power of voice", Journal of Finance
- Nagase et al. (2024), APSIPA ASC
What are your calls telling you?
Signal transcribes collections calls live and puts what the customer says to work.
Contact